
Life doesn’t stop after you obtain insurance. Maybe you added that much-needed extra bathroom to your home or inherited your grandparents’ precious antiques. Perhaps your teenager is going off to college or you’re starting a new business. You will likely need to adjust your coverage to align with your new circumstances.
Here are 16 life experiences that should prompt you to call us:
Getting married or divorced
Many insurance companies offer benefits, like marriage discounts, multicar discounts and bundled insurance policies. You may have wedding or engagement rings that are insured. If you’re going through a divorce, let us know. (Some divorce decrees specify insurance requirements.) You should adjust your policies, update names and review your life insurance beneficiaries.
Buying, renting or moving to a new residence
A new house or rental will need new coverage. It would be terrible to lose your home in a fire, only to find out you’re not insured. Make sure your policy limits are high enough to cover the cost of rebuilding your home based on market value.
Even if you don’t own a place, you and your belongings need protection. A renters insurance policy will cover your personal belongings and offer added liability coverage in case someone is injured on your property or sues you.
Purchasing a new car
Tell us if you’ve bought a new car. We’ll need the model and vehicle identification number (VIN). Depending on your old and new vehicles, your insurance rate may change significantly, either up or down.
Becoming a business owner, even if it’s a home-based business
No matter where your business is located or how big it is, you’ll probably need coverage to ensure everything is protected. Take note of your business operations. If you use your car for business or store merchandise and supplies at home, you’ll need extra coverage. Ask us if a business owners policy is right for you.
Doing home renovations
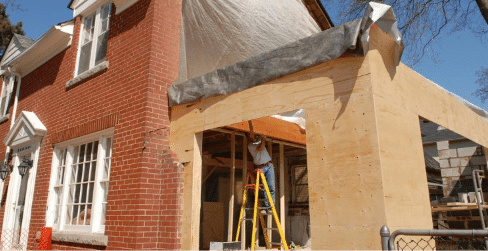
Major improvements to your home can put your at risk of being underinsured. Major improvements include adding a room, remodeling your kitchen or enclosing a porch. An increase in the structure’s value may require an increase in your home insurance coverage limits.
Having a new teen driver
When your teenager gets their driver’s license, they need to be properly insured. Getting insurance for them can be pricey, so make sure they attend all the necessary driver’s education classes. And remember to inform us so you can take advantage of any discounts.
Acquiring something expensive
Any time you inherit or buy something valuable, reevaluate the contents coverage portion of your home insurance policy. The policy limits may not be high enough. Compare the cost of increasing insurance on your valuables versus the cost of adding an umbrella policy to expand coverage over your home and auto. You can get an umbrella policy with $1 million or more in coverage.
Going to college
If your college student is moving into on-campus or off-campus housing, review your insurance policies to ensure their personal possessions and vehicle are adequately covered.
Joining a carpool
If you’re a regular carpool driver, your liability insurance should reflect the increased risk of additional passengers in the vehicle.
Installing a security alarm or smart home system
Security systems deter theft. Some smart home systems, like whole-house water shut-off systems, can prevent catastrophic structural damage. Call us about insurance discounts for these systems, even if you’re only in the planning stages
Switching mortgage or auto lenders
Claims payments can get confusing if your old lender is still listed on your policy. Your insurance company may need to issue a check to you and your lender when there’s a claim. Listing the wrong lender can delay claim processing or premium payments and leave you temporarily uninsured.
Driving less
Working from home, living closer to your office or joining a carpool will reduce your mileage. Auto insurance companies consider less mileage a lower risk, so you might be rewarded with a lower rate.
Buying a second home
Don’t skimp on the insurance. This is especially important if your second home will be vacant for long periods. If you rent your second home, ask us about landlord insurance.
Traveling internationally
If you plan to drive outside Canada, your current coverage may not protect you abroad. For example, Mexico requires all drivers to have Mexican auto insurance. They don’t recognize Canadian auto insurance. You can be fined or jailed, in addition to not being covered in an accident.
Having your identity stolen
If you’ve been the victim of this kind of crime, you may want identity theft or cyber liability coverage to protect yourself and your family in the future.
Retiring
You might be able to get a discount on your home insurance when you retire. If you commuted regularly to your job, your annual mileage may drop significantly.
Remember to update us as your circumstances change. We’ll help you offset your financial liability and protect what’s important to you.